IBM links Digital Asset Haven to Swift ledger work for tokenized deposit rails
IBM is extending Digital Asset Haven so regulated institutions can connect operational wallet and transaction controls to Swift’s emerging blockchain ledger work. The move matters because tokenized deposits need bank-grade governance, not just settlement-speed claims.
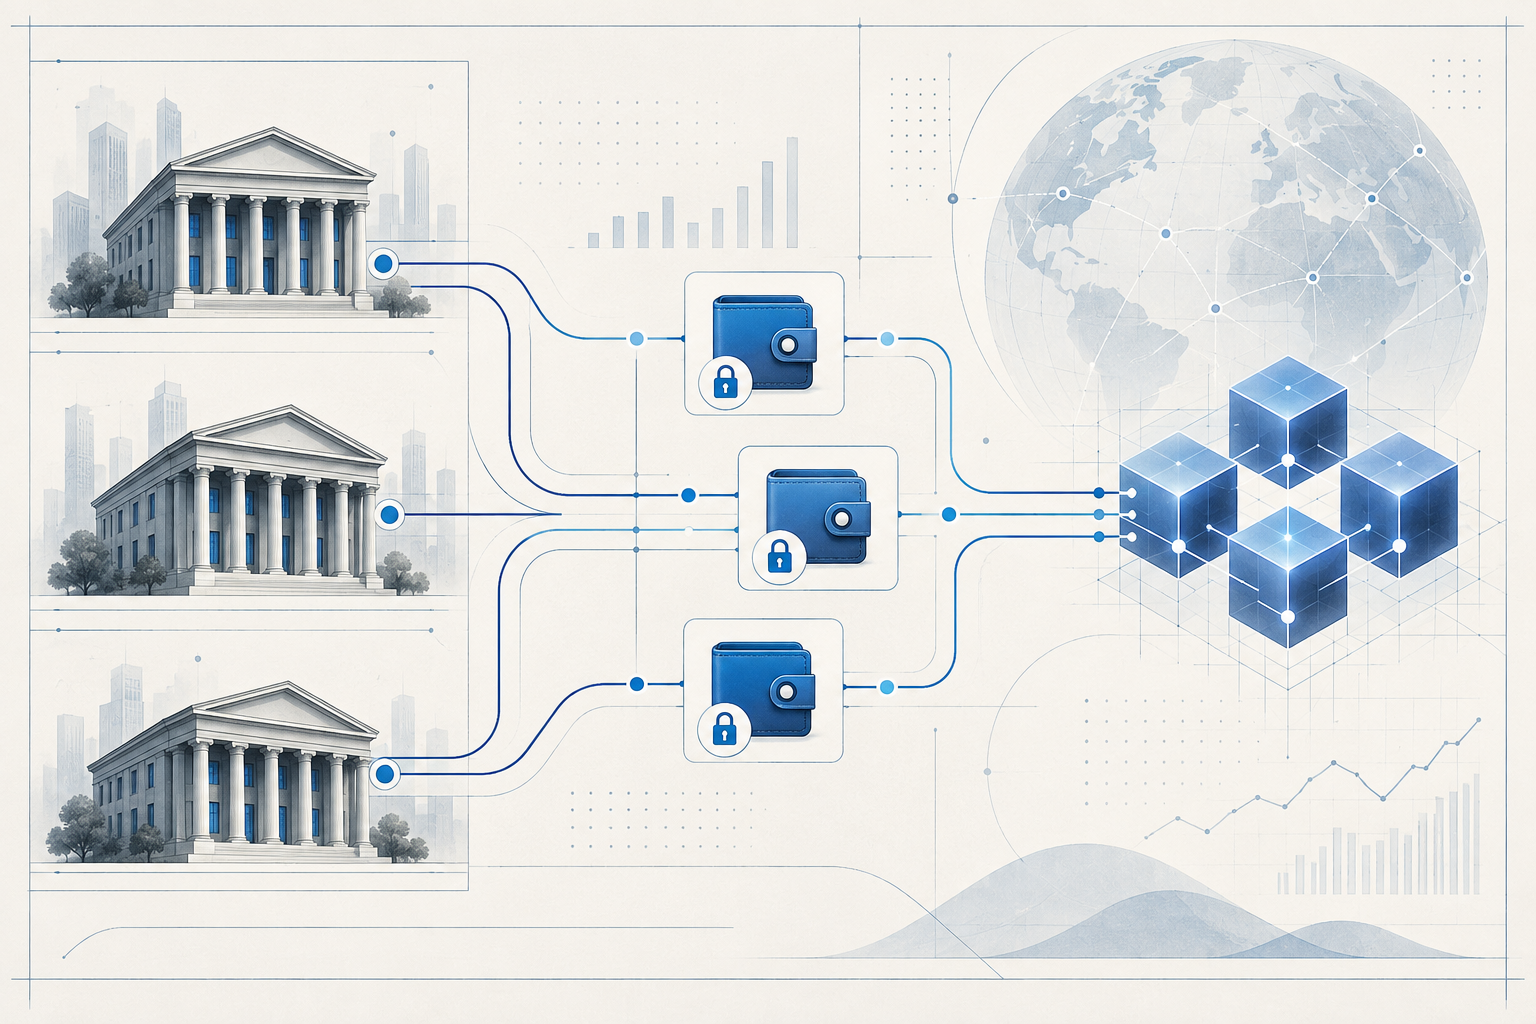
IBM is pushing its digital-asset infrastructure closer to the banking core by adding a Swift ledger integration path to IBM Digital Asset Haven, giving financial institutions a more direct way to test tokenized deposit workflows against familiar compliance and operational controls. The update is not a consumer stablecoin launch, and it does not mean a full production Swift settlement network is live. It is a bank-infrastructure story: the connective tissue between custody, wallet policy, transaction orchestration and a shared ledger model for deposits.
The key product change is the IBM Digital Asset Haven Swift Ledger MVP, which IBM describes as a way for financial institutions to connect to Swift’s blockchain-based shared ledger for tokenized deposit transactions. IBM’s own product materials frame Digital Asset Haven as an operational backbone for regulated enterprises entering digital assets, with wallet management, transaction orchestration, governance, key management and integration into existing banking systems. That positioning matters because tokenized deposits are only useful to large banks if they can be operated inside existing risk, approval and audit frameworks.
Swift has been exploring a shared-ledger architecture as part of a broader effort to make digital finance interoperable with the correspondent-banking network and bank messaging layer that already moves institutional money globally. The strategic idea is straightforward: banks do not want isolated token networks that create new liquidity silos. They want tokenized money and tokenized assets to move with consistent identity, controls and settlement instructions across jurisdictions and counterparties. IBM’s integration gives institutions a practical vendor route to test those flows from a secured operations platform rather than a standalone blockchain experiment.
Digital Asset Haven is built around institutional controls that are often missing from early-stage tokenization pilots. IBM lists multiparty computation, hardware security modules and confidential-computing components as part of the security model, alongside programmable governance and permissioning for transaction approvals. It also says the platform can support transaction formatting, broadcasting, routing intelligence, lifecycle visibility, travel-rule data and failure recovery through APIs. For banks, those features are not secondary; they are the gating items that decide whether a tokenized deposit workflow can survive operational-risk review.
The integration also arrives alongside IBM’s expansion of deployment models for Digital Asset Haven. IBM’s current materials describe SaaS, hybrid and on-premises options, including a beta path for fully client-controlled deployments on LinuxONE infrastructure. That is important for deposit institutions and market-infrastructure firms that may not be comfortable placing signing infrastructure or sensitive transaction controls entirely in a vendor-hosted environment. The ability to choose between faster onboarding and stronger client-side control could widen the set of banks able to participate in pilots.
For the RWA market, tokenized deposits sit in a different bucket from fiat-backed stablecoins but address a similar settlement problem. Stablecoins such as USDC and USDT have already shown demand for programmable dollar settlement outside traditional bank hours. Tokenized deposits aim to keep the liability closer to regulated banks while preserving some of the same 24/7 transferability and programmability. If Swift-linked bank deposit tokens mature, they could become a preferred settlement asset for regulated tokenized funds, securities and treasury workflows that need bank balance-sheet money rather than public stablecoin exposure.
The remaining questions are execution questions. Institutions still need clarity on legal treatment, finality, liquidity management, cross-border supervision and how a shared ledger would interact with existing payment systems. A minimum viable product also does not answer whether banks will commit live volume or merely continue controlled experimentation. But IBM’s role is notable because it addresses the unglamorous layer that determines adoption: security architecture, approval policy, integrations and deployment control.
The broader signal is that tokenized-deposit infrastructure is moving from research papers into vendor-supported implementation paths. That does not guarantee near-term production volume, but it does make the next phase more concrete. If banks can test tokenized deposits through platforms that fit their operating model, RWA settlement can start to look less like a crypto integration project and more like a modernization track for institutional money movement.