Canada’s largest banks start work on a shared tokenized-deposit network
RBC, TD, BMO, Scotiabank, CIBC and National Bank are jointly exploring a Canadian-dollar tokenized-deposit system, beginning with transfers between the banks themselves. The project puts commercial-bank money, not a retail CBDC, at the center of Canada’s next digital settlement experiment.
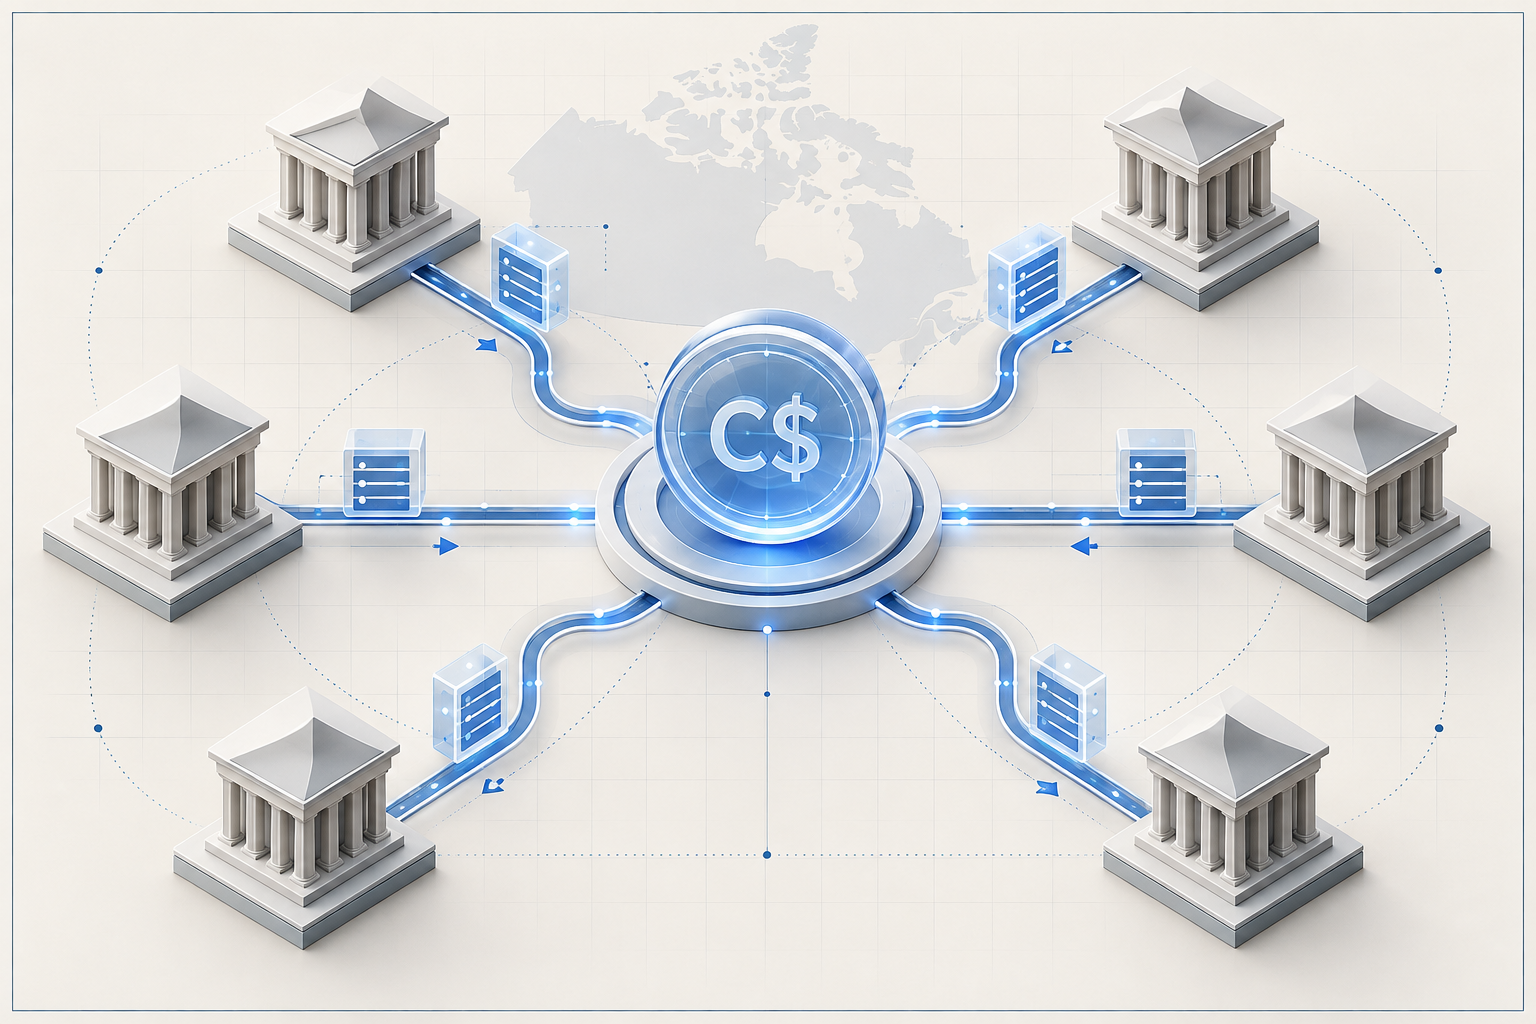
Canada’s six largest banks are jointly exploring a Canadian-dollar tokenized-deposit network, a move that puts commercial-bank money at the center of the country’s next digital settlement experiment. Royal Bank of Canada said the group includes RBC, TD Bank Group, BMO, Scotiabank, CIBC and National Bank of Canada, with the first phase focused on transfers between the participating institutions rather than a consumer-facing wallet launch.
The project is designed around tokenized deposits: digital representations of bank deposits that remain liabilities of regulated deposit-taking institutions. That makes the model different from an open stablecoin issued by a crypto company and different again from a central bank digital currency. In practice, the banks are examining whether shared ledger infrastructure can move deposit claims between institutions more efficiently while preserving the legal and supervisory framework that already governs bank money.
The initial scope is deliberately narrow. The banks are starting with interbank transfers, which allows them to test settlement mechanics, reconciliation, governance and operational controls before expanding to broader payment use cases. That sequencing is important because a shared deposit network has to solve practical questions that consumer payment apps can abstract away: finality, reversibility, identity, sanctions screening, account mapping, liquidity management and the treatment of failures across multiple institutions. It also keeps the experiment close to the institutions that already manage settlement risk, rather than pushing a new money format directly into retail circulation before the operating model is proven.
The Canadian effort also lands in a policy environment where the central bank has studied a digital dollar without committing to issuance. The Bank of Canada previously ran public consultations on a potential digital Canadian dollar and has continued to track changes in payments, stablecoins and consumer-driven banking. A bank-led tokenized-deposit rail gives policymakers another path to evaluate: upgraded commercial-bank settlement infrastructure that could coexist with existing payment systems and reduce the immediate need for a retail CBDC.
For the participating banks, the strategic logic is defensive and offensive at the same time. Stablecoins have shown that tokenized cash can move across digital venues with speed and programmability, but they also introduce questions about reserves, consumer protection, redemption, and the boundary between payments and shadow banking. Tokenized deposits offer banks a way to adopt some of the same programmability while keeping money creation and customer relationships inside the regulated banking sector.
That does not make implementation easy. A multi-bank deposit token requires common technical standards, shared governance, clear legal treatment of the token record, and agreement on how messages and funds move between core banking systems and ledger infrastructure. The system also has to prove that it improves on existing rails, whether through faster settlement windows, lower reconciliation costs, richer payment data or new programmable-payment capabilities for institutions. Without those benefits, a tokenized-deposit pilot risks becoming a technology demonstration rather than market infrastructure.
The cross-border angle is also worth watching. Canada’s banks serve corporate clients that move money across North America and globally, while U.S. banks and payment companies are separately studying stablecoins, deposit tokens and tokenized cash platforms. If domestic bank-led networks mature, the next question will be interoperability: whether tokenized deposits can communicate with wholesale settlement systems, stablecoin networks, securities platforms and foreign bank money without fragmenting liquidity.
For RWA markets, the Canadian bank initiative reinforces a broader pattern. Tokenization is no longer limited to funds, bonds and equity wrappers; the cash leg of transactions is being rebuilt as well. A credible tokenized-deposit network could make settlement for tokenized securities and other real-world assets more bank-compatible, especially for institutions that want programmable rails without leaving the commercial banking system.