Canada’s largest banks move tokenized deposits into shared testing
Canada’s six largest banks are testing a common tokenized-deposit model for interbank movement of commercial bank money. The project keeps the settlement asset inside regulated banking while testing the programmability that stablecoins brought to market first.
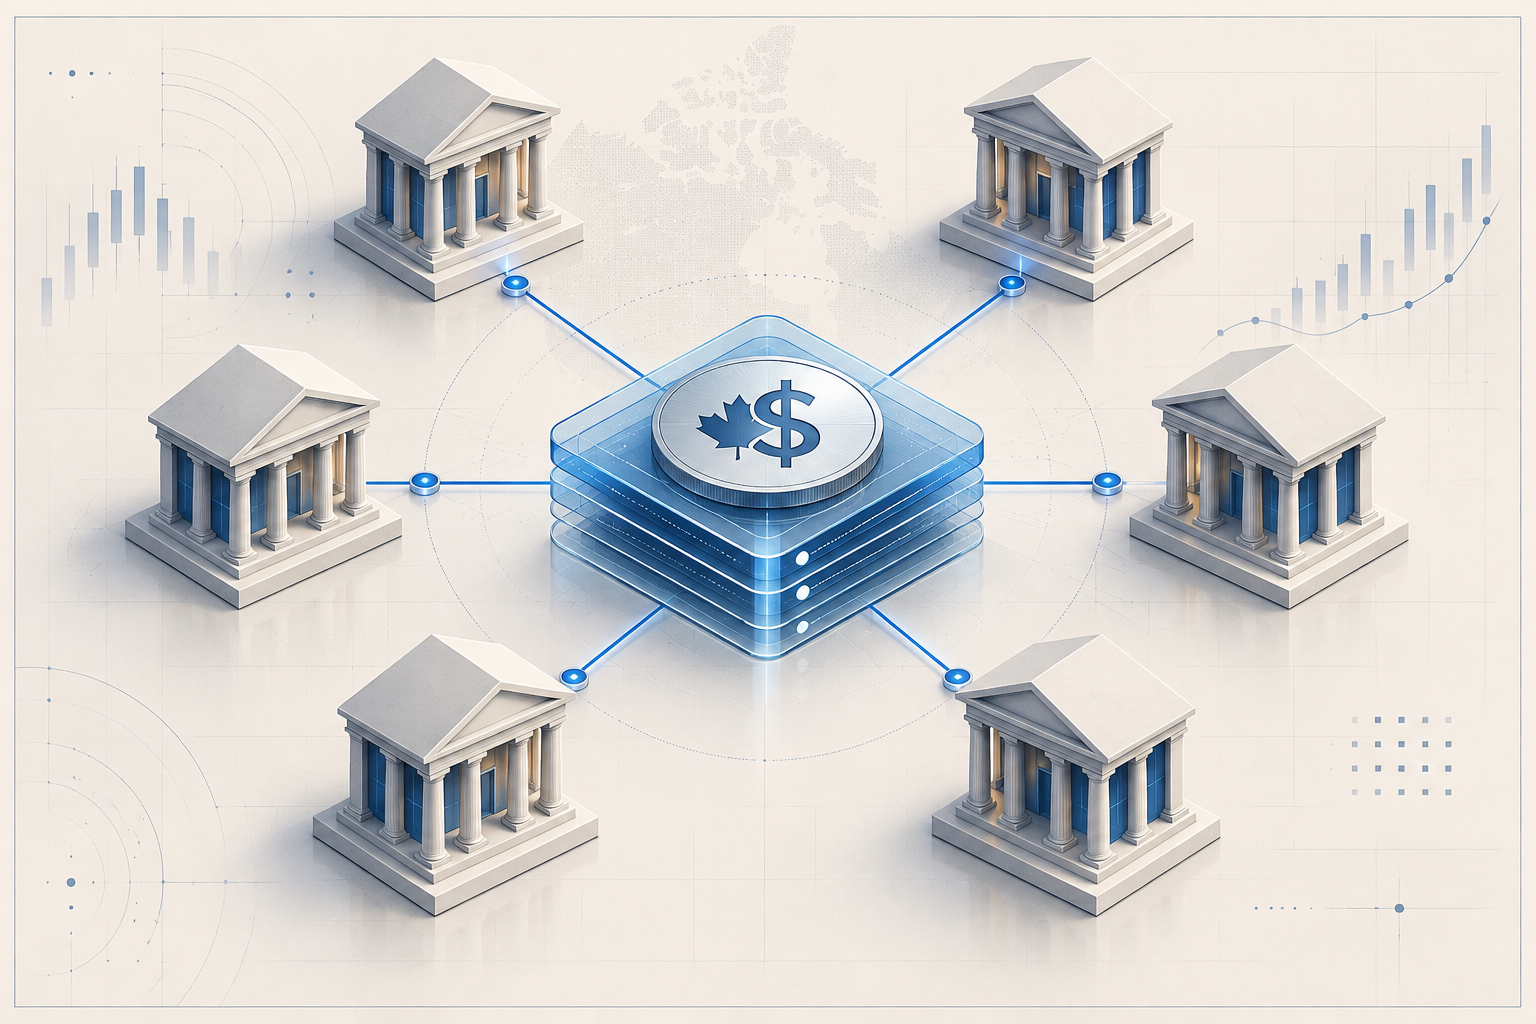
Canada’s largest banks are moving tokenized deposits from a single-institution experiment into a shared banking-system test. Bank of Montreal, CIBC, National Bank of Canada, Royal Bank of Canada, Scotiabank and TD Bank Group are working on a Canadian-dollar tokenized deposit initiative designed first for interbank movement of commercial bank money, with a longer-term path toward links with other digital asset infrastructure.
The near-term scope is narrow by design. The first phase is focused on moving digital representations of existing bank deposits across participating institutions. That distinction matters: a tokenized deposit is not a standalone crypto-issued stablecoin, and it is not meant to sit outside the banking perimeter. It is a claim on money already held at a regulated bank, represented on digital rails so it can be transferred and programmed more efficiently.
For Canada, the significance is less about a retail product launch and more about market structure. The country’s dominant banks are testing whether deposit money can gain some of the operational features associated with stablecoins — faster settlement, programmable payment logic and potential 24/7 availability — without shifting customers into a privately issued non-bank token. If the model works, banks could offer clients digital money that behaves more like internet-native settlement while retaining familiar supervisory, balance-sheet and compliance frameworks.
The project also fits into a wider Canadian tokenization push. Earlier work around Project Samara tested issuance, trading and settlement of a C$100 million bond on distributed ledger technology using tokenized wholesale Canadian dollars. That pilot brought the Bank of Canada and major banks into the same practical question now facing global capital markets: how can cash and securities legs move on compatible rails without creating new settlement risk?
Tokenized deposits are gaining momentum because they address a specific institutional concern. Stablecoins have proven demand for blockchain-based dollars, but many banks and corporates still prefer settlement assets that remain inside commercial bank money or central bank money frameworks. A shared tokenized-deposit network could give banks a way to support programmable payments, treasury workflows and future tokenized securities settlement while preserving deposit relationships rather than ceding activity to external issuers.
There are still open questions. Governance will be the decisive issue: participants need common rules for token minting and redemption, intraday liquidity, dispute handling, node operation and how the system behaves if one bank or technology provider is unavailable. The banks have not committed to broad issuance, public access, blockchain selection, operating hours, interoperability standards or a production date. Any live system would need robust controls for identity, reversibility, operational resilience, liquidity treatment and regulatory reporting. The harder challenge is not proving that a digital deposit can move on a ledger; it is proving that several large institutions can agree on a common model that works across balance sheets and risk systems.
Internationally, the timing is notable. The shared approach also reduces the risk of each bank building a separate token that cannot move cleanly across counterparties, which would reproduce the same fragmentation tokenization is supposed to solve. Banks in the United States, Europe and Asia are testing tokenized deposits alongside central-bank money bridges and wholesale settlement networks. Swift has also been working with banks on tokenized-deposit interoperability for cross-border payments. The direction of travel is clear: regulated institutions are trying to make bank money more composable before stablecoins become the default settlement layer for digital asset activity.
For RWA markets, Canada’s initiative is important because tokenized assets need a credible cash leg. Tokenized bonds, funds and private-market instruments become more useful when money can settle with similar speed and programmability. A six-bank Canadian deposit test does not guarantee production adoption, but it raises the odds that future Canadian-dollar tokenized securities will have bank-native payment rails instead of relying entirely on offshore dollar stablecoins.